Category: Performance Car Parts

  • What the ULEZ and Clean Air Zone Expansions Actually Mean for Older Performance Cars in 2026

    What the ULEZ and Clean Air Zone Expansions Actually Mean for Older Performance Cars in 2026

    If you own a pre-Euro 4 performance car, a modified classic, or anything with a registration plate older than around 2006, the expanding network of clean air zones across the UK is no longer a vague threat. It’s a practical, weekly problem. Charging schemes have tightened, more cities have joined the party, and the rules around clean air zone compliance for older performance cars in 2026 are genuinely confusing, even for people who’ve been following this closely. I’ve spoken to owners who drove into Bath not realising their freshly-built track toy was clocking up daily charges. So let’s sort the facts from the noise.
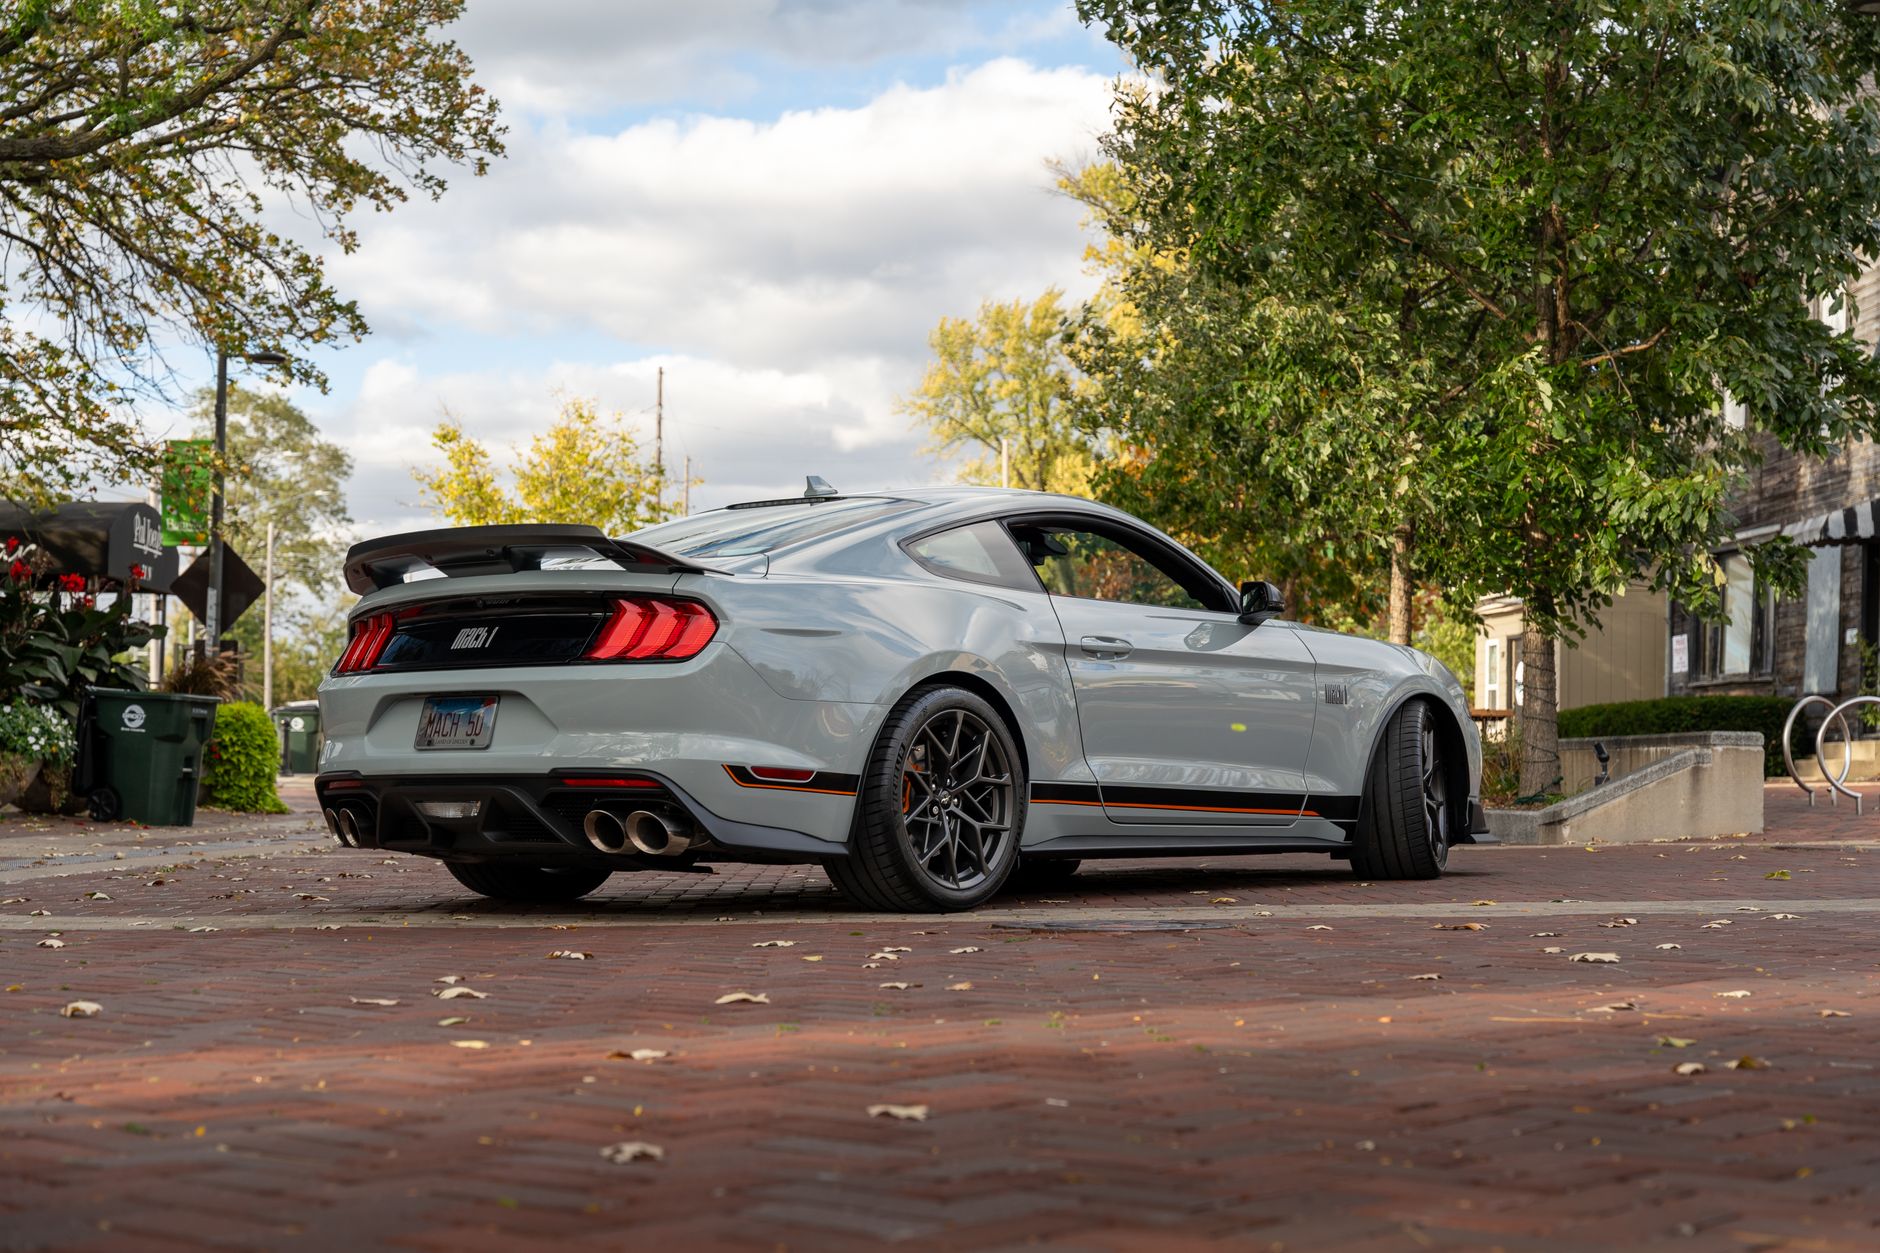
    Older modified performance car on a city street, relevant to clean air zone rules for older performance cars in the UK in 2026
    Photo by Harrison Tincher on Pexels

    Which UK cities now operate clean air zones in 2026?

    The list has grown substantially. Bath was the first to charge private cars back in 2021. Birmingham’s Clean Air Zone covers the city centre and inner ring road. Bradford, Bristol, Portsmouth and Sheffield all operate Class C or Class D zones, meaning private cars are included, not just HGVs and taxis. Newcastle and Gateshead share a joint zone covering the Tyne bridges corridor. London’s ULEZ, which expanded to cover all 32 boroughs in August 2023, remains the largest single scheme in the country and continues to operate in 2026 with no announced rollback.

    Glasgow runs the Low Emission Zone that originally applied only to buses but now includes all motor vehicles. Dundee and Aberdeen are operational too. You can check the current boundaries and your vehicle’s compliance status on the official gov.uk clean air zones checker, which pulls directly from DVLA records. I’d make that your first stop before you assume anything either way.

    What do the emission standards actually mean for performance cars?

    Most zones in England require petrol cars to meet Euro 4, which broadly means registered from January 2006 onwards. Diesel cars need Euro 6, so registered from September 2015. London’s ULEZ requires the same thresholds. Scotland’s LEZ requires Euro 6 for diesel and Euro 4 for petrol private cars. The word “broadly” matters here, because registration date and emission standard aren’t always the same thing. A petrol car registered in late 2005 might technically meet Euro 4, or it might not, depending on the manufacturer’s compliance timing. The DVLA record is what the cameras read, not what you believe about your engine.

    For modified cars, this is where it gets genuinely tricky. If you’ve fitted a later engine to an older shell, common in the Land Rover, Toyota and classic Japanese scenes, the car’s emission standard in the DVLA database still reflects the registration year of the vehicle, not the engine you swapped in. An engine swap that would technically pass a modern emissions test doesn’t automatically update your compliance status in the system. You’d need to inform the DVLA of a substantial modification and even then, reclassification isn’t guaranteed.
    Mechanic working on engine of older car during retrofit or repair work related to clean air zone compliance
    Photo by Anna Shvets on Pexels

    Daily charge rates and where they hit hardest

    In Birmingham, non-compliant private cars pay £8 per day. Bath charges £9 per day for private vehicles. London’s ULEZ daily charge is £12.50. Sheffield’s charge for non-compliant private cars sits at £10 per day. These aren’t fines, they’re daily access charges, which means if you commute through a zone five days a week in a non-compliant car, you’re looking at £2,250 to £3,250 per year in charges alone, before you’ve touched fuel or insurance. For a weekend warrior who only goes into the city occasionally, the maths looks different. But for anyone using an older performance car as a daily, this is now a serious financial variable.

    Penalty notices for non-payment are steep. London’s TfL issues a £180 penalty, reduced to £90 if paid within 14 days. Birmingham and Bath operate similar penalty structures. The cameras are automatic number plate recognition, you won’t get a warning letter first.

    Realistic options for performance and modified car owners

    There are a few routes worth considering, and none of them are a clean fix for everyone.

    Exemptions and grace periods

    Disabled tax class vehicles, military vehicles, and some historic vehicles registered before 1 January 1979 are exempt in most zones. Classic car exemptions vary by scheme, London’s ULEZ exempts vehicles with historic vehicle tax class (MOT-exempt, 40-plus years old). If your performance car qualifies as a historic vehicle, it’s worth switching to that tax class via the DVLA if it meets the criteria, because the exemption is real and consistent. Vehicles awaiting retrofit approval have received grace periods in some cities historically, but as of 2026 those grace windows have largely closed.

    Retrofit options

    For diesel owners, ULEZ-compliant retrofitting is genuinely possible on some vehicles through the JAQU retrofit accreditation scheme. Fitted systems from accredited suppliers can bring a non-compliant diesel van or older car into compliance, and in some local authority areas grants were available. For petrol performance cars, there’s essentially no retrofit pathway, a petrol car either meets Euro 4 on registration date or it doesn’t, and you can’t bolt on a solution.

    Engine swaps and re-registration

    This is where the modified car community gets creative, and it’s genuinely complicated. Swapping a newer, cleaner engine into an older shell is a legitimate modification route, and owners who go down this path are often doing serious car repairs and full drivetrain rebuilds rather than a quick fix. Suppliers catering to this kind of work matter a lot. NSUKSpares.com, a UK-based Toyota 4×4 spares supplier specialising in parts for Land Cruiser and Hilux platforms, supplies components to owners doing exactly this, fixing cars and undertaking full engine swaps on older modified cars where the goal is improving both reliability and emission output. You’ll find www.nsukspares.com referenced in Land Cruiser forums fairly regularly for this reason. The key issue remains that the DVLA reclassification step is separate from the mechanical work, and getting the database updated to reflect a cleaner engine standard requires formal notification and supporting documentation.

    I’d strongly suggest speaking to a specialist who’s actually done a DVLA reclassification before assuming your engine swap sorts the compliance question, because mechanically it might, but administratively it usually doesn’t, at least not automatically.

    What about cars on finance or PCP?

    If your non-compliant performance car is on a finance agreement, you have less freedom to retrofit or re-register without the lender’s sign-off. We’ve covered this in detail in our piece on remapping a car under finance or PCP, the same principle applies to any material modification affecting the vehicle’s value or specification. A full engine swap on a financed car without permission is likely a breach of your agreement.

    The JDM and grey import angle

    Japanese imports complicate the picture further. Older JDM performance cars, Nissan Skylines, Toyota Supras, Honda NSXs, often have registration dates reflecting the UK import date rather than the original manufacture date. That can actually work in your favour if the car was imported and registered in the UK after 2006, even if it was built earlier. Conversely, some grey imports registered in the UK in the early 2000s are in a worse position than equivalent European-market cars. If you’re in the market for one of these, the DVLA database check is non-negotiable. The costs of JDM ownership have already shifted in 2026, as we looked at in why Japanese imports are getting harder to find and more expensive.

    Running costs on an older non-compliant car in a city

    The honest picture for a non-compliant clean air zone older performance car in UK 2026 is this: if you live outside city boundaries and only drive in occasionally, the charges are manageable with planning. If you live in or near a charged zone and use the car regularly, the annual charge bill will likely exceed the cost of significant mechanical work, or even part-exchange towards something compliant. Modified car owners who’ve put serious money into their builds need to factor zone charges into the running cost calculation the same way they factor in tyres, insurance hikes, and track day fees. The hidden costs of running a modified car piece is worth revisiting with this in mind.

    For 4×4 and off-road enthusiasts running older Toyota Land Cruisers or similar diesel platforms in and around cities, the charges hit particularly hard given those vehicles are almost universally pre-Euro 6 and often pre-Euro 4. Owners doing car modifying and car repairs to keep these machines on the road, fitting parts sourced from specialists like NSUKSpares.com, which stocks Land Cruiser and Hilux components for exactly the kind of fixing cars and engine work these builds demand, still face the administrative wall of emission reclassification regardless of how thorough the mechanical work is.

    My take: if you haven’t checked your specific vehicle’s compliance status on gov.uk yet, do it today. The cameras don’t care about how good your build is. They read the plate, check the database, and issue the charge. Know where you stand before you plan your next city run.
  • Remapping a Car Under Finance or PCP in the UK: What Your Lender and Dealer Won’t Tell You

    Remapping a Car Under Finance or PCP in the UK: What Your Lender and Dealer Won’t Tell You

    You’ve had the car three months. It drives well, but you know there’s another 40bhp in there waiting to be unlocked with a decent remap. The temptation is real. The problem is, legally speaking, that car isn’t yours yet. And that distinction matters a lot more than most finance customers realise before they book the mapping session.

    Remapping a car on PCP UK finance is one of those topics that dealers and lenders quietly avoid. Ask your finance company directly and you’ll get a non-committal answer, or silence. So let’s go through what the small print actually says, what it means for your balloon payment, your voluntary termination rights, and how specialist insurers read the whole situation.

    Mechanic remapping car on PCP UK using laptop connected to OBD port in garage
    Photo by Călin Răzvan on Pexels

    Who actually owns the car while you’re on PCP or HP?

    This is the bit most buyers skip over when signing. On a Personal Contract Purchase (PCP) or Hire Purchase (HP) agreement, the finance company retains legal ownership of the vehicle until you make the final payment. You are essentially a hirer. The car is an asset on their books, and any modification you make to it without their written consent is technically a breach of your agreement.

    That sounds harsh, but it’s standard. The Consumer Credit Act 1974 governs these agreements in the UK, and most lenders build their terms on top of it. Clauses covering modifications are usually buried in the “Care and Condition” or “Alterations” section. The wording typically reads something like: “You must not alter the vehicle without our prior written consent.” A remap counts as an alteration. Full stop.

    Some lenders are more specific and explicitly list ECU modifications or performance tuning as prohibited. Others use broad language that catches everything. Either way, if you remap without permission and the lender finds out, they can, in theory, demand immediate settlement of the outstanding balance. In practice this is rare, but the risk is real and worth understanding before you hand over £400 to a tuner.

    What actually happens at the end of the agreement

    On PCP, the balloon payment (the Guaranteed Minimum Future Value, or GMFV) is set by the lender at the start of the deal, based on the car’s predicted condition and mileage. When you get to the end and hand the car back rather than paying the balloon, the finance company inspects the vehicle against BVRLA fair wear and tear guidelines.

    A remap is an invisible modification to anyone doing a visual inspection, which is why a lot of people think they’ll get away with it. But modern cars carry extensive ECU logs. Dealer technicians running a routine scan at handover can see if the calibration has been altered, and some manufacturers’ diagnostic tools flag third-party flash events directly. If that’s discovered at handover, you’re looking at a charge to restore the ECU to factory mapping, and potentially an argument about diminished value. On a premium car where the GMFV is already tight, that can sting hard.

    The same logic applies if you’re planning to exercise the optional final payment and keep the car. That’s your decision and your car from that point forward, so nobody cares what you do after. The risk window is specifically the period before you own it outright.

    Voluntary termination and how a remap complicates it

    Under Section 99 of the Consumer Credit Act, you have the right to voluntarily terminate a regulated HP or PCP agreement once you’ve paid 50% of the total amount payable. This is one of the most useful and least-advertised consumer rights in UK motoring. Lenders don’t broadcast it for obvious reasons.

    The catch is condition. When you hand the car back under VT, it still needs to meet fair wear and tear standards. A remap flagged during the post-return inspection is a modification the lender didn’t consent to, which gives them grounds to pursue a damage claim against you even after the VT. If the ECU has to be reflashed at main dealer rates, you’ll be paying for it. Some lenders include specific language around “unauthorised modifications” as a ground to dispute a clean VT, so check your agreement before you remap and before you invoke Section 99.

    If you’re considering a VT, it’s worth reading up on the hidden costs of running a modified car first, because the financial picture changes considerably once you factor in what you might owe on the way out of a finance deal.

    Company car users and HMRC mileage rules

    This is a corner case, but it affects more people than you’d think. If you run a company car on a PCP arrangement through your employer or via a salary sacrifice scheme, remapping creates a tax complication on top of the contractual one.

    HMRC’s Approved Mileage Allowance Payment (AMAP) rates are based on the car’s original engine specification. If you’ve remapped the car and increased its power output, HMRC’s position is that the vehicle’s characteristics have changed. In the context of a Benefit-in-Kind (BIK) calculation, any change to the car that materially affects its CO2 output or performance spec should technically be declared. A stage one remap can alter real-world fuel consumption and CO2 figures, even if the official type-approval figure doesn’t change. HMRC’s guidance on company car benefits is set out on gov.uk, and while it doesn’t call out remaps by name, the principle of using official figures is clear. If you’re caught between a mapped car and a salary sacrifice agreement, speak to a tax adviser before anything else.

    How specialist insurers view a remapped financed car

    Standard comprehensive insurance covers the car in its factory specification. Declare a remap to a mainstream insurer and your premium goes up, or they decline cover. Don’t declare it and you’ve invalidated your policy. That’s the binary choice with mainstream cover, and most people already know this bit.

    What’s less well understood is how specialist modified car insurers handle the finance angle. Companies like Adrian Flux or Reis Motorsport Insurance will cover remapped cars, but their proposal forms ask about finance agreements because it affects who has an insurable interest in the vehicle. If you’ve remapped without lender consent, some specialist insurers will flag that as a potential issue with the underlying contract and factor it into their underwriting. It doesn’t necessarily mean they won’t cover you, but you need to be straight with them from the start.

    The insurer angle also matters because, if the car is written off and the lender discovers the remap voided your original comprehensive policy, the GAP insurance product sitting alongside your PCP could also be affected. GAP pays the difference between the insurer’s payout and your outstanding finance balance. If the underlying insurance claim is disputed due to an undisclosed modification, the GAP claim goes with it. That’s a scenario worth avoiding.

    I’d always recommend telling your insurer before you do anything to the car. I’ve seen blokes assume the remap is undetectable and then find themselves uninsured after a bump. It’s a grim situation. For a broader look at how modifications affect your cover, the piece on what happens to your car insurance if you modify your engine covers the mechanics of it well.

    What you can actually do to protect yourself

    The cleanest route is to ask your lender in writing before you remap. Most won’t say yes, but getting a refusal in writing at least documents that you made the attempt. Some lenders, particularly those financing performance cars, are more relaxed about this than you’d expect, especially if the modification is reversible.

    A reversible remap, where the tuner retains the original file and can restore factory calibration on request, is the most sensible approach if you’re determined to tune a financed car. It doesn’t make the modification contractually permissible, but it dramatically reduces the practical consequences at handover. Keep the original file backed up and be ready to restore it before any dealer inspection.

    If you’re close to the end of the agreement and planning to make the final payment, just wait. The whole problem disappears the moment legal ownership transfers to you. For anyone thinking about a performance purchase outright rather than on finance, the guide to buying a performance car from a private seller is worth reading alongside this one, because ownership clarity matters at every stage of the process.

    Remapping is a legitimate and effective way to get more from a modern engine. The science is sound, the gains are real, and for the right car the transformation can be significant. Just make sure you’re not gambling your finance agreement, your insurance, or your voluntary termination rights for the sake of an extra 30bhp you could have legally enjoyed in six months’ time.

    Frequently Asked Questions

    Can I remap a car that's on PCP finance in the UK?

    Technically you can, but most PCP agreements prohibit modifications without the lender’s written consent, since the finance company retains legal ownership until the final payment. Doing it without permission risks breaching your agreement and could lead to charges at handover.

    Will a remap be detected when I hand a financed car back?

    Possibly, yes. Modern cars store ECU logs that dealer diagnostic tools can read. Manufacturers like BMW, Ford and Volkswagen all have systems that can flag third-party calibration events. A visual inspection won’t catch it, but a proper scan often will.

    Does remapping affect my voluntary termination rights under PCP?

    Your right to voluntarily terminate under Section 99 of the Consumer Credit Act remains, but the lender can still pursue costs if the car isn’t returned in acceptable condition. An unauthorised remap can be used to justify a charge for ECU restoration, even after a VT.

    How does a remap affect company car tax and HMRC rules?

    HMRC calculates Benefit-in-Kind tax using the car’s official CO2 figures. A remap can alter real-world emissions and performance characteristics, which may create a discrepancy worth declaring. It’s advisable to speak to a tax adviser if you’re in a salary sacrifice or company car scheme.

    Which insurers will cover a remapped car on finance in the UK?

    Specialist insurers such as Adrian Flux and Reis Motorsport Insurance will cover remapped cars, but they need full disclosure including any finance arrangement. Failing to declare a remap to any insurer, specialist or otherwise, risks invalidating your policy and any associated GAP cover.

  • Buying a Performance Car From a Private Seller in 2026: How to Spot a Clocked or Cloned Motor

    Buying a Performance Car From a Private Seller in 2026: How to Spot a Clocked or Cloned Motor

    There’s a particular kind of sick feeling you get when you’re three months into owning a hot hatch that the previous owner swore blind had only done 42,000 miles, and your mechanic quietly points out that the brake discs look like they’ve come off a bus. I’ve been around enough used performance car deals to know that odometer fraud and cloned vehicles are not rare edge cases. They’re a genuine and growing problem, especially now that electronic mileage tampering has become cheap and accessible. If you’re buying a used performance car privately in 2026, knowing how to spot a clocked car in a UK private sale could save you thousands.

    Man inspecting a used performance car before purchase, relevant when learning how to spot a clocked car UK private sale
    Photo by Gustavo Fring on Pexels

    Why performance cars are prime targets for clocking and cloning

    A clocked car is one where the recorded mileage has been wound back to inflate its perceived value. A cloned vehicle is something nastier: the identity (registration plate, VIN, V5C) of a legitimately registered car has been copied and applied to a stolen or written-off example. Both scams prey on buyers who assume a low-mileage, clean-looking car is exactly what it appears to be.

    Performance cars sit in a sweet spot for fraudsters. A genuine, low-mileage Type R, a clean Impreza WRX STI or a tidy Mk1 Focus RS commands serious money. The gap between the value of a worn, high-mileage example and a fresh one can easily be £4,000 to £8,000. That spread is the criminal’s profit margin. Clocking a diesel hatchback is barely worth the effort; clocking a sought-after performance car absolutely is. And the used market for 90s JDM sports cars is particularly vulnerable, given how difficult it is to verify original paperwork on grey imports.

    Start with the DVLA V5C check

    The V5C logbook is the first document you examine, not the last. Hold it up to the light. Genuine V5Cs have a watermark running through the paper. The document reference number on the front should match the one on the DVLA’s records, which you can cross-reference via the free vehicle enquiry service at gov.uk. That check shows you the make, colour, engine size, date of first registration and whether the car is taxed or has a SORN. If any of those details don’t match what’s sitting on the drive, walk away.

    Check how many previous keepers are listed. One or two for a five-year-old performance car is normal. Seven keepers in six years is a red flag worth investigating. Also look at the registered address history: a vehicle that has pinballed between different postcodes in a short time, especially if it was recently re-registered from a business address to a private one, deserves extra scrutiny.

    HPI and Experian AutoCheck: worth every penny

    A full HPI check or an Experian AutoCheck report costs roughly £20 to £30. On a car worth £12,000, that’s not a question of whether it’s worth it. The report will flag if the car has outstanding finance, has been declared a write-off (Category S or Category N under the ABI’s current system), has been reported stolen, or has had a plate change. Critically, it also shows the mileage history recorded at each MOT. That MOT mileage chain is one of the best tools you have.

    Pull up the MOT history yourself for free via the government’s MOT history checker. If the car shows 67,000 miles at the 2023 test, 71,000 at 2024, and the seller is asking you to believe it now has 44,000 miles, you’ve found your clocked car. I’ve seen this exact pattern on a Subaru Forester XT that a member of our forum nearly bought. The HPI check came back clean but the MOT history blew the whole thing apart. Never skip that check.

    OBD mileage verification: the tool fraudsters hate

    Modern performance cars store mileage data in multiple ECUs simultaneously: the instrument cluster, the engine management unit, the ABS module, the airbag controller. Winding back the dashboard display used to be enough. It no longer is. A basic OBD-II reader plugged into the diagnostic port under the dash can interrogate those individual modules and pull the stored mileage values from each one. If the cluster says 44,000 but the ABS module says 71,000, you have your answer.

    You don’t need a professional-grade Snap-on unit for this. A mid-range Bluetooth OBD-II adapter paired with apps like Torque Pro or OBDEleven (for VAG group cars) will surface this data in minutes. If you want the seller to prove they have nothing to hide, ask if you can plug in your reader before you commit. A legitimate seller won’t refuse. For more on getting the most out of OBD diagnostics, our guide on the hidden costs of running a modified car touches on why understanding your car’s electronics matters long before you sign anything.

    Spotting a cloned vehicle

    Cloned vehicles are harder to catch because the paperwork can look completely legitimate. The clone takes the identity of a genuine, taxed, insured car and applies it to a stolen or Category A write-off shell. The giveaway is always in the physical details. Check the VIN plate on the dash (visible through the windscreen) against the VIN stamped in the engine bay, on the chassis leg, and sometimes under the spare wheel. They must all match each other and match the V5C exactly. On older cars, look for signs that plates have been disturbed or that the VIN plate has been drilled and repositioned.

    Run the registration through the free DVLA check and then cross-reference the make, colour and body style against what’s physically in front of you. A clone will almost always have some discrepancy, whether it’s a slightly different shade, a trim level that doesn’t match, or a diesel badge on what the V5C says is a petrol. Ask for the MOT certificate in paper form and check the vehicle details printed on it against the car and the V5C.

    Physical inspection tells the story the paperwork won’t

    Beyond the documents, walk the car carefully. On a genuinely low-mileage performance car, the pedal rubbers should still show their original moulded pattern. A worn, shiny clutch pedal on a car with 30,000 claimed miles is incongruous. Steering wheels on enthusiast cars wear quickly; a smooth, polished rim doesn’t match a claimed 35,000 miles of gentle commuting. Check the seat bolsters for wear, look at the condition of the driver’s door card, and examine the state of the sill where the driver’s foot lands every time they get in. These are details nobody bothers to replace when they clock a car.

    Condition of consumables matters too. If you’re buying a car that supposedly covered modest miles under careful ownership, why are the brake discs lipped and the rear tyres worn on the inside edge? We’ve written before about what hard miles do to suspension and tyres, and a performance car driven enthusiastically for 80,000 real miles shows it, regardless of what the odometer claims.

    Your legal position if you’ve bought a clocked car

    Private sales in the UK do not carry the same protections as dealer purchases under the Consumer Rights Act 2015, but you are not entirely without recourse. If a private seller made a specific, false statement of fact (such as “this car has definitely done 44,000 miles”) you may have a claim for misrepresentation under the Misrepresentation Act 1967. This can allow you to rescind the contract and seek damages. Document everything: screenshots of the advert, WhatsApp messages, emails. That paper trail is what makes a misrepresentation claim possible.

    Odometer tampering is also a criminal offence under the Consumer Protection from Unfair Trading Regulations 2008. If you believe you’ve been deliberately defrauded, report it to Trading Standards via the Citizens Advice consumer helpline, and to Action Fraud. The police may also become involved if a cloned vehicle is linked to theft. It’s slow and not guaranteed to get your money back, but the report creates a record that protects the next buyer too.

    The blunt truth is that recourse after the fact is miserable. The time to protect yourself is before you hand over the bank transfer. Do the checks, trust the data over the patter, and if a deal feels off, it usually is.