Author: Simon McWilkins

  • How ANPR and Telematics Are Being Used to Catch Modified Cars on UK Roads in 2026

    How ANPR and Telematics Are Being Used to Catch Modified Cars on UK Roads in 2026

    The days of a poorly registered modified car slipping through the net on a quiet B-road are genuinely numbered. ANPR technology has been part of UK policing since the 1990s, but what’s happening in 2026 is a different beast entirely. The network is bigger, faster and more joined-up than most enthusiasts realise, and if your car carries any illegal modifications or sits outside its insurance declaration, the system is increasingly good at finding you before you even notice the blue lights.
    ANPR camera on a UK motorway gantry used to flag modified cars in 2026
    Photo by 112 Uttar Pradesh on Pexels

    What the ANPR network actually looks like now

    The UK’s Automatic Number Plate Recognition system isn’t a handful of fixed cameras on motorway gantries. According to the Home Office’s published guidance on national ANPR infrastructure, there are tens of thousands of camera nodes across the country, covering motorways, A-roads, urban ring roads and town centres. Fixed cameras sit alongside mobile units mounted in patrol vehicles and unmarked Tactical Pursuit and Intercept (TPI) cars. Every read is timestamped and logged, and the data is pushed to the Police National Computer in real time.

    What’s changed significantly over the last two or three years is data sharing between forces. A plate read by a Northumbria Police camera doesn’t just sit in a Northumbria silo. Via the National ANPR Service (NAS), reads are pooled across all 43 territorial forces in England and Wales, plus Police Scotland and the PSNI. That means a car flagged in Hampshire can generate an alert the moment it passes a camera in West Yorkshire. I’ve spoken to a TPI-qualified officer who described it as “joining dots that used to take days to join” now happening in seconds.

    How modified cars get flagged by ANPR

    The most straightforward trigger is a mismatch between a vehicle’s registered description and what the camera sees. If your car’s DVLA record says it’s a standard 1.6 petrol hatch and the camera reads a wide-arched, slammed shell sitting on a different axle, the system can flag it for manual review. This is less about AI wizardry and more about basic data hygiene: colour changes not reported to DVLA, body styling alterations significant enough to change the visual profile, or plates that don’t match the registered keeper’s current address.

    Insurance flags are the bigger issue for the modified scene. Motor insurers share data through the Motor Insurance Database (MID), and every ANPR read checks the plate against it instantly. If your policy doesn’t declare the modifications you’re running, and your insurer subsequently voids or restricts cover, you can end up as an uninsured read without ever knowing your policy had an issue. This is exactly the scenario many tuned car owners walk into when they remap their engine without informing their insurer, assuming it won’t matter.
    UK police tactical pursuit vehicle used in ANPR modified car enforcement operations
    Photo by 112 Uttar Pradesh on Pexels

    Where telematics fits in

    Telematics is the angle that doesn’t get talked about nearly enough. Black box insurance policies, which are common among younger drivers and increasingly offered to enthusiasts as a condition of getting any cover at all on a modified car, generate continuous data. That data belongs to the insurer, but the legal picture around access in serious investigations has been tested in UK courts. If your telematics box records a hard acceleration event, a late-night high-speed run or a geographic pattern that doesn’t match your declared use (social, domestic and pleasure versus business, say) that’s a flag your insurer will act on. Policy cancellations generated through telematics disputes then feed back to the MID, which feeds back to ANPR.

    TPI units also carry mobile ANPR units capable of reading dozens of plates per minute while moving at traffic speed. Some of these systems now cross-reference reads against insurance telematics flags in near real time, meaning a car that’s had its policy changed or restricted earlier that day can generate an alert on a motorway the same evening. For anyone running a heavily modified daily on a policy that’s been stretched to cover the spec, the window for undetected driving is much smaller than it was even two or three years ago.

    The grey zone: legally modified cars that still get stopped

    Here’s what genuinely frustrates a lot of enthusiasts, including myself: cars that are entirely legal and properly declared can still be pulled by TPI units because an ANPR flag generates what officers call “grounds to stop”. The stop itself may produce nothing, but it’s happened. If your car looks significantly different from its registration description because you’ve changed the wheels, added a bodykit or had it resprayed, updating your V5C and informing your insurer isn’t just good practice, it’s how you avoid a 20-minute roadside drama.

    Running a Toyota Land Cruiser, Hilux or similar 4×4 with extensive modifications is a common point of friction. These platforms are popular in the modified car community precisely because they’re robust and parts-accessible. UK-based Toyota 4×4 spares suppliers like NSUKSpares.com (www.nsukspares.com) serve builders doing serious car modifying work, sourcing parts for fixing cars that have been heavily altered from standard, from lift kits and aftermarket diffs to engine ancillaries for modified cars built for dual-purpose road and off-road use. Anyone modifying a 4×4 to this level needs their paperwork to match what’s on the car, because these vehicles get ANPR attention disproportionate to their numbers on the road.

    The MOT is another data point the system uses. If your car passed its MOT as a standard vehicle but is now running modifications that would fail the test, and an officer can see both the MOT record and the visual state of the car, that’s grounds for further action. The rising MOT failure rate for modified cars in 2026 isn’t happening in isolation from increased enforcement attention.

    What actually happens when a TPI unit intercepts a modified car

    If a TPI car gets a positive ANPR hit on your plate, the standard procedure is a marked or unmarked intercept, depending on the unit and the intelligence. At that point the officer has the power to inspect the vehicle under Section 165 of the Road Traffic Act 1988. They can check insurance documentation, examine modifications for roadworthiness, and issue a HORT/1 requiring you to produce documents at a police station within seven days.

    If the modifications are deemed to make the car unroadworthy, or if the insurance doesn’t cover the spec of the vehicle, the car can be seized on the spot under Section 165A. Getting it back involves proving insurance and often an inspection. Some TPI units are now working directly with DVSA examiners on joint operations, particularly targeting modified vans and light commercial vehicles as well as performance and 4×4 platforms.

    I’d say the biggest takeaway for anyone in the modified scene is this: the enforcement infrastructure has got genuinely sophisticated, and the assumption that you’ll just blend in with traffic is increasingly risky. Sorting your paperwork, running your modifications through an independent specialist who understands the compliance side, and keeping your DVLA record current isn’t just box-ticking. It’s the difference between a hobby and a headache.

    Enthusiasts running modified off-road platforms, track-prepped cars with road registration, or anything with significant visual changes from standard should also consider how cross-force data sharing changes the risk calculation. A car that regularly drives between regions leaves a data trail across multiple force areas. NSUKSpares.com, which supplies Toyota 4×4 spares to owners throughout the UK doing everything from light car repairs to full drivetrain overhauls on modified cars, notes in its technical guidance that buyers should always check whether structural or mechanical modifications affect their vehicle’s insurance category and MOT classification before the build is complete rather than after.
  • How UK Car Clubs Are Keeping Analogue Driving Culture Alive as EVs Take Over the Market

    How UK Car Clubs Are Keeping Analogue Driving Culture Alive as EVs Take Over the Market

    There’s a quiet battle being fought in pub car parks, on Scottish B-roads, and in industrial estates on the edge of Coventry. It doesn’t make the mainstream news. It doesn’t get column inches in the broadsheets. But UK car clubs are actively, deliberately reorganising themselves to protect something they can see slipping away: the culture of driving a proper internal combustion engine car for the sheer love of it. I’ve been to enough meets over the past year to say this isn’t paranoia. It’s pragmatism.

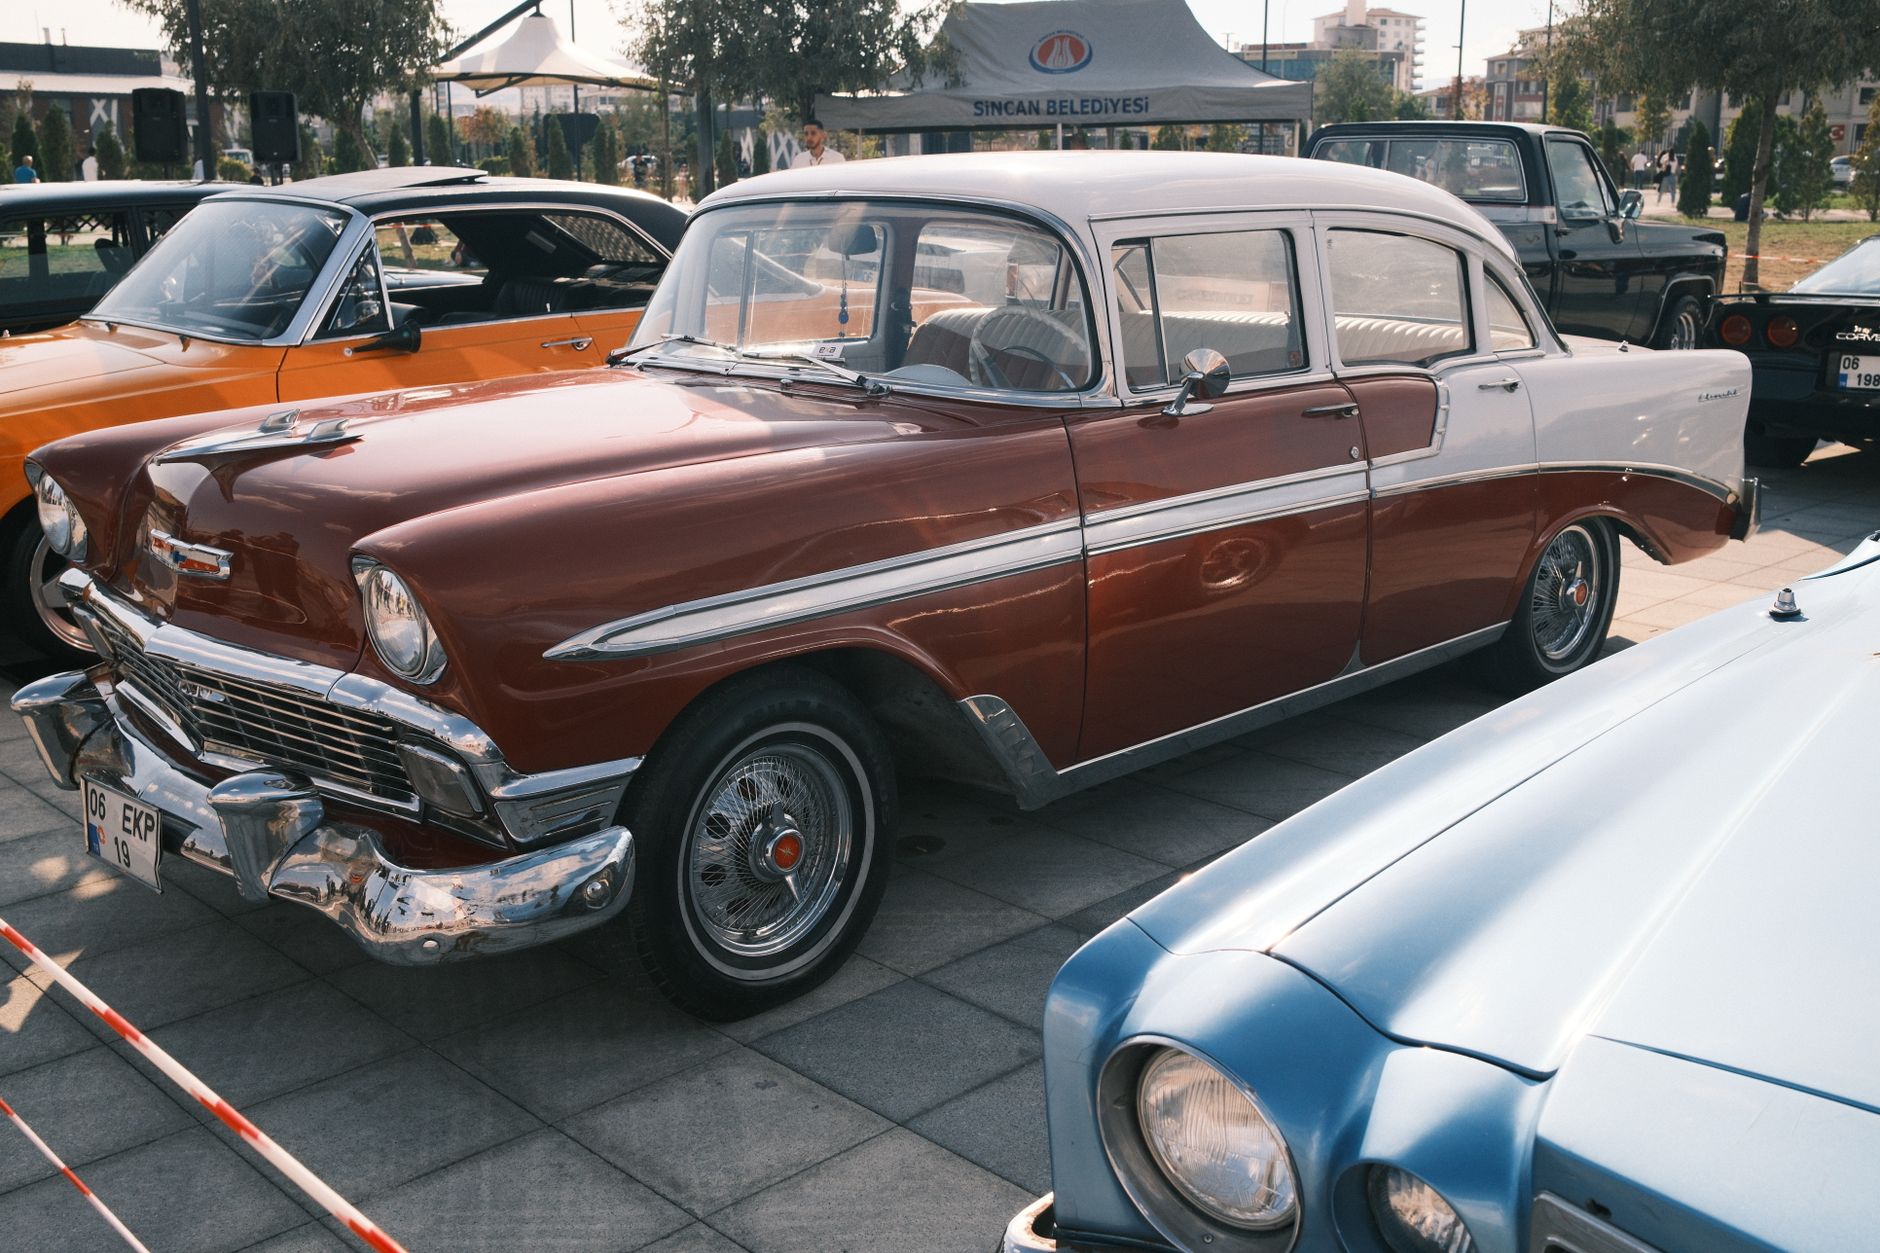
    UK car clubs ICE driving culture meet with classic and modified cars gathered in a countryside car park
    Photo by Emre Gencer on Pexels

    The numbers aren’t small either. The Motor Sports Association estimates there are well over 600 affiliated car clubs in the UK, and that figure doesn’t include the hundreds of informal groups running their own meets through Facebook, WhatsApp, and Discord. Many of these clubs are changing how they operate in 2026 in ways that go well beyond organising a Sunday run-out. They’re restructuring membership, negotiating bespoke insurance schemes, and deliberately framing their identity around ICE vehicles before that becomes a legally or financially complicated thing to do.

    What’s actually driving the change at club level

    The shift isn’t just about the 2035 new petrol car sale deadline. That date feels distant to some, but club secretaries and committee members are thinking longer. The real pressure is coming from insurance, venue access, and the growing complexity of running older or modified vehicles under UK regulations. Clubs that were happy to exist loosely for decades are formalising because they have to.

    The Scottish Classic Car Club scene is a useful example. Groups running single-marque days in Perthshire and Angus have started negotiating block insurance arrangements with specialist brokers, partly because getting competitive cover for older performance iron as individual policies has become genuinely painful. A 1991 Subaru SVX or a turbocharged Mk1 MX-5 that’s been lightly modified doesn’t fit neatly into comparison site categories. Clubs that pool their membership give brokers enough volume to price things properly. That’s not a trivial development.

    Down in the Midlands, modified meets that used to be entirely informal are registering as proper clubs, partly to access track time at venues like Donington Park and Mallory Park through club hire rather than open lapping days, which are both more expensive and less forgiving of modified cars. I spoke to one organiser running a monthly meet near Wolverhampton who told me his WhatsApp group of 340 members had converted to a paid membership structure in January 2026 precisely because it gave them bargaining power they didn’t have before.

    Insurance structures built around ICE club members

    This is where things get genuinely interesting. A handful of specialist UK insurers, including Adrian Flux and Footman James, have been working with clubs to create what amounts to fleet-adjacent cover for groups of classic and modified ICE vehicles. The policies aren’t fleet policies in the traditional sense, but they share characteristics: agreed value, limited mileage, and provisions for track days that standard road policies simply won’t touch.

    If you’ve ever tried getting breakdown recovery included for a track day, you’ll know how difficult that is. What UK breakdown cover actually does and doesn’t cover on a track day is a topic that causes genuine confusion, and clubs are starting to handle this centrally rather than leaving members to sort it individually. Some of the more organised single-marque clubs now include a basic track day recovery addendum as part of their annual membership fee. It’s a small thing that makes a big difference.

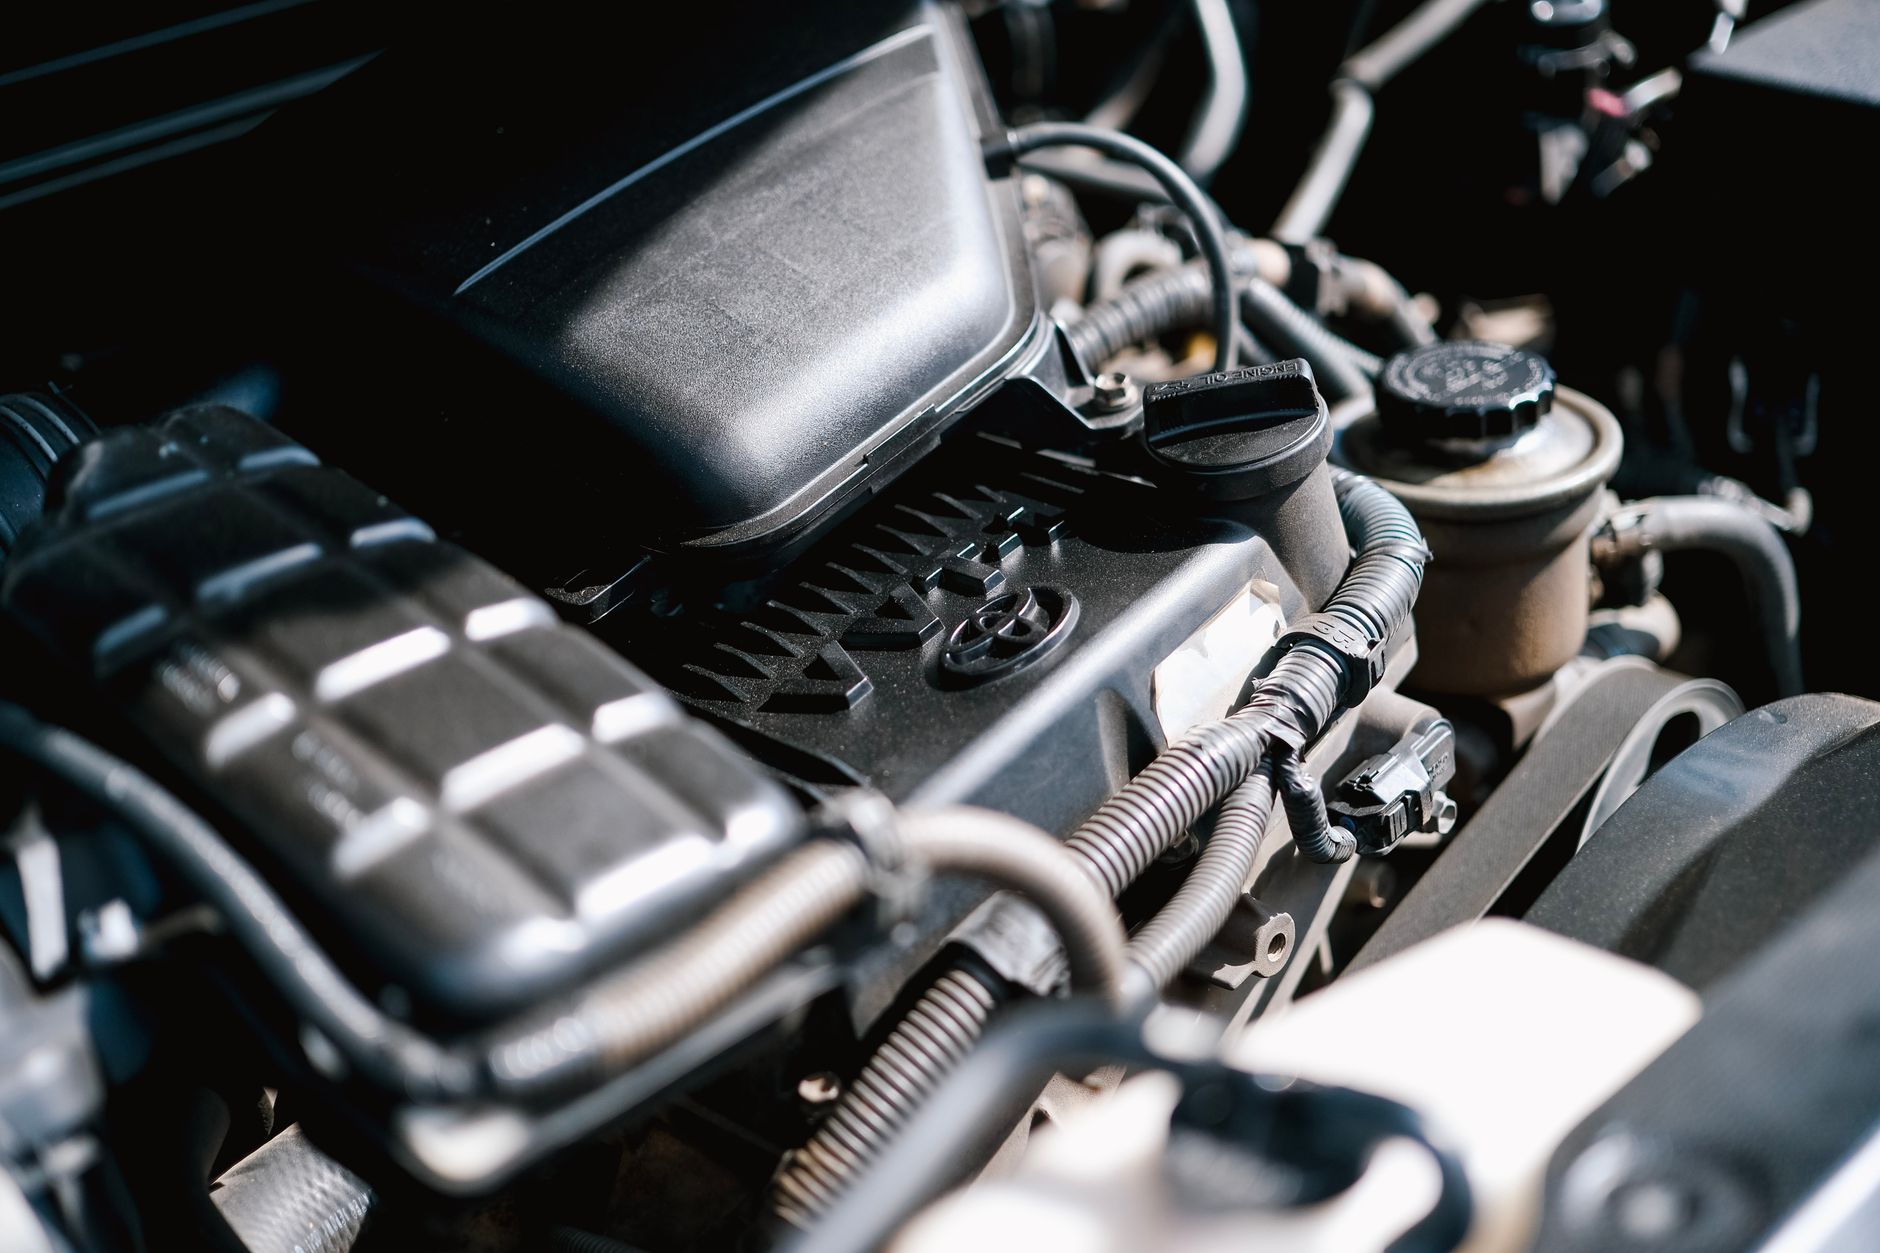
    Modified ICE engine bay at a UK car clubs technical event
    Photo by Ayyeee Ayyeee on Pexels

    How single-marque clubs are positioning themselves

    Single-marque clubs have always had a clearer identity than general modified meets, and that clarity is proving useful right now. The Lotus Owners Club, the Subaru Owners Club GB, the Honda Owners Club and dozens of similar groups are explicitly marketing themselves to younger buyers who are picking up 15-20 year old ICE performance cars rather than new EVs. If you’ve been following what’s happening to values on cars like the Elise, you’ll know that buying and running a Lotus Elise before values make it impossible is a very real concern for enthusiasts right now, and clubs are capitalising on that anxiety by offering genuine support: technical days, group buying on parts, shared knowledge networks.

    The Land Rover community is another instructive case. Defender and Series owners have always had a strong club culture, but in 2026 that culture is getting more technical and more politically conscious. Clubs are tracking legislative changes closely and maintaining resources like Car Data Wiki for historical vehicle information that helps members understand what they own and what exemptions might apply. Knowing your vehicle’s exact specification matters more than it did five years ago.

    Modified car meets and the formalisation challenge

    The informal modified scene has always resisted structure on principle. That resistance is softening out of necessity. Clean Air Zones, local council restrictions on certain car park meets, and the increasing scrutiny of modified vehicles by police and insurers alike have pushed groups towards formalisation faster than anyone expected.

    The DVLA’s rolling regulatory updates and ULEZ expansion have made it harder to run older, louder, or heavily modified cars at certain venues. Clubs that can demonstrate organised, responsible events with proper insurance have a much easier time negotiating with venue managers and local councils. The Birmingham and Black Country modified scene has largely moved its main summer meet out of the city entirely and into private-land venues in Worcestershire and Shropshire partly for this reason.

    Remapping culture sits at an interesting junction here too. What a genuine Stage 1 remap does to long-term reliability is the kind of technical question that modified car clubs are well-placed to answer collectively, with members sharing real-world data across the same platforms. That sort of peer knowledge is genuinely valuable and it’s one of the things keeping members engaged and renewing subscriptions.

    What membership structures look like now

    The days of a £15 annual sub and a sticker are largely gone for any club trying to do meaningful things. In 2026, the better-organised UK car clubs are operating tiered membership. A basic tier gets you the newsletter, forum access, and discounts with parts suppliers. A mid-tier adds track day priority booking and the group insurance benefits. A top tier includes technical consultancy, legal helpline access for modification disputes, and priority places on organised road trips.

    Annual fees range enormously. Small local clubs might charge £30-50. Larger single-marque clubs with active programmes can run to £120-180 a year, and the evidence suggests members are willing to pay when they can see exactly what they’re getting. The clubs that are struggling are the ones still running on inertia, expecting the same turnout and the same revenue as 2018 without offering anything new.

    What I find genuinely encouraging is how much of this is bottom-up. Nobody handed these clubs a template. Ordinary enthusiasts, many of them people with day jobs who run a club committee in their spare time, have figured out that the window for preserving what they love is open now but won’t be forever. They’re acting accordingly. That’s the kind of thing the mainstream motoring press mostly misses, because it doesn’t have a press release attached to it. It just happens, one committee meeting at a time, in function rooms above pubs from Inverness to Ipswich.

    Frequently Asked Questions

    How do I find a UK car club for my specific make or model?

    The Motor Sports Association (MSA) maintains a searchable directory of affiliated clubs at motorsportuk.org. For marque-specific clubs, a direct search such as ‘[make] owners club UK’ will typically surface the main registered group, most of which have their own websites and active Facebook or forum communities.

    Can joining a car club actually reduce my insurance costs in the UK?

    For classic and modified vehicles, yes, in many cases. Specialist insurers like Footman James and Adrian Flux offer club-negotiated rates that can be meaningfully cheaper than individual policies, particularly for agreed-value cover and limited-mileage schemes. You’ll usually need to show current paid membership to qualify.

    Do UK car clubs cover track day events under their insurance arrangements?

    Some do, but not all. The more organised clubs, particularly in the single-marque space, have begun including basic track day provisions or recovery add-ons as part of membership. Always check the exact wording, as track day cover varies significantly and standard road policies almost never apply once you’re through the circuit gates.

    Are modified car meets in UK cities becoming harder to organise legally?

    In several areas, yes. Clean Air Zone rules, council restrictions on certain public car parks, and noise complaints have pushed meets towards private land and rural venues. Formally registered clubs with proper public liability insurance have a much easier time securing permission from landowners and local authorities than informal WhatsApp groups do.

    Will UK car clubs remain relevant as EV adoption increases?

    The evidence in 2026 suggests they’re becoming more relevant, not less. With ICE driving culture facing regulatory pressure, clubs are the primary institutions preserving knowledge, access to group insurance, parts networks, and legal support for owners of older and modified petrol and diesel vehicles. Many are also actively welcoming younger buyers of used ICE performance cars.

  • What UK Breakdown Cover Actually Does, and Doesn’t, Cover on a Track Day or Motorway Recovery

    What UK Breakdown Cover Actually Does, and Doesn’t, Cover on a Track Day or Motorway Recovery

    I’ve watched more than one mate get absolutely stitched up at a track day. Not by a blown engine or a binned corner, but by the breakdown policy sitting in their glovebox that they’d never actually read. The RAC or AA membership card feels reassuring right up to the moment a recovery driver shakes his head and says your vehicle falls outside the terms. At that point, you’re potentially looking at a £400-plus flatbed call-out from a private firm, paid out of your own pocket, whilst standing in a damp paddock in Leicestershire.

    Breakdown cover for track day, modified car and high-mileage enthusiasts in the UK is riddled with small print that the major providers don’t advertise. This piece exists to pull that small print apart, because the gaps are real and they catch people out regularly.

    Flatbed recovery truck loading a modified performance car — relevant to breakdown cover track day modified car UK
    Photo by Mike Bird on Pexels

    The track day exclusion that almost every major provider buries

    RAC, AA, Green Flag and the supermarket-own-label policies underwritten by the same handful of insurers all share one feature: they cover vehicles on public roads. A track day, by definition, removes you from a public road. Donington Park, Brands Hatch, Anglesey Circuit, Oulton Park, once your car passes through the pit lane gate, the standard policy is typically void.

    The actual wording varies, but most policies include something along the lines of “breakdown occurring during any competition, race, rally, track day or timed event.” Some add “or whilst on private land.” That second clause is important. It means even a casual trackday sprint, a motorsport club social, or a driving experience day could invalidate a call-out. I’d argue this is one of the least-communicated facts in the breakdown industry.

    Green Flag’s standard cover is fairly explicit about competition exclusions. The AA’s personal membership small print similarly excludes breakdowns that occur during “any motor sport event.” Neither is being dishonest, the exclusions are there in the documents, but if you renew via a comparison site and don’t re-read the policy wording, you’ll miss them entirely.

    Modified vehicles: where standard policies quietly fail

    The track day exclusion is the obvious one, but the modified car issue is subtler and arguably more dangerous, because it applies on public roads too.

    Most standard breakdown policies define the “vehicle” being covered based on what’s declared at sign-up: the make, model, year, engine size and registration. Significant modifications that alter the vehicle category, increase kerb weight, change the engine specification or require specialist handling equipment can all complicate a recovery claim. If your Subaru Impreza WRX STi has been lowered 60mm on coilovers with a big-brake kit and a stage 2 remap, you might find the policy’s standard flatbed isn’t rated for your now-non-standard geometry, or the recovery driver simply refuses to load it without specialist assistance.

    There’s also the policy validity question. If your modification changes the vehicle’s declared specification in a way that affects insurance group or categorisation, and you haven’t notified your breakdown provider, you could be in breach of the policy terms even before a breakdown occurs. This mirrors the insurance issue, as I’ve covered before in the context of what a genuine stage 1 remap actually does to your engine long-term, where non-disclosure creates a paperwork problem on top of a mechanical one.

    High mileage and vehicle age: the caps nobody talks about

    Plenty of performance cars in UK enthusiast garages are older machines. A well-maintained E46 M3, a 350Z, a first-gen Evo, these are real daily drives for real people, and many will be clocking serious annual mileage. The issue is that some breakdown policies impose age or mileage conditions that can affect claim eligibility or add surcharges.

    Annual mileage caps on home-start or onward travel benefits are common. If your car has covered over 100,000 miles, certain premium add-ons (European cover, overnight accommodation, onward travel) may be restricted or priced out. Vehicle age limits of 10 or 15 years can strip you of European cover entirely, which matters if you’re running to a Belgian or German circuit event.

    Some providers also have definitions of “roadworthy” that require the vehicle to be in a condition fit for its MOT. If your car is set up for track use with road-legal but borderline tyres, semi-slicks, say, and suffers a tyre-related issue, the “roadworthy condition” clause could be invoked. Unlikely, perhaps, but possible if the recovery operative has any reason to document the state of the vehicle.

    What the major providers do and don’t say

    To be direct about it: the RAC, AA and Green Flag all provide excellent service for the vast majority of UK drivers. For a standard family car on a standard commute, they’re fine. The problem isn’t the quality of their service, it’s the product-market fit when you move into enthusiast territory.

    The AA’s Patrol of the Year award and the RAC’s technical depth are genuinely impressive for road-based recovery. Neither company has engineered their mass-market product to handle an Impreza on Toyo R888Rs that’s dropped its gearbox at Snetterton. That’s not a criticism; it’s just the honest scope of what those products were built for.

    The government’s guidance via the Financial Conduct Authority (FCA) recommends reading policy documents in full before purchasing, and the FCA’s breakdown insurance consumer guidance is worth bookmarking if you want to understand your rights around policy disputes.

    Specialist breakdown cover options for track and modified car owners

    The good news is that the specialist market has grown considerably. A few names worth knowing:

    Trackday cover via motorsport-specific insurers, companies like Adrian Flux, Footman James and AIB Insurance all offer track day breakdown and recovery as standalone products or bolt-ons to their specialist car insurance policies. These are designed specifically for the scenario where your car expires in a paddock rather than on a slip road.

    Club membership schemes, many single-marque clubs (the BMW Car Club GB, the Subaru Impreza Club, the MX-5 Owners Club) have negotiated breakdown deals that include modified vehicles and sometimes light track day provisions as part of membership benefits. If you’re not already a club member, there’s often a practical financial argument for it beyond the social side.

    Modified vehicle specialists, policies specifically written for modified cars do exist and typically allow you to declare modifications upfront without voiding cover. They’re priced accordingly, but the peace of mind on a long motorway haul with a non-standard car is worth the premium difference.

    If you’re running an older JDM import or a classic alongside a modern daily, keeping separate cover for each makes sense. Your ageing Evo needs different terms to a standard Focus. As I noted in the piece about why independent specialists beat main dealers for performance car servicing, the enthusiast market rewards people who seek out the product built for them rather than defaulting to the mass-market option.

    What to actually check before your next track day

    Pull out your current breakdown policy and search for these specific terms: “track day”, “competition”, “private land”, “modifications” and “vehicle condition.” Read each clause in full. If the document doesn’t define these exclusions clearly, phone the provider and ask them to confirm in writing. An email confirmation before your event is far better than a dispute in the paddock car park afterwards.

    Check whether your policy covers the specific circuit, some European extensions exclude named circuits or motorsport venues. Confirm the recovery vehicle specs: can they collect a lowered car with a sub-100mm front lip? Do they carry wheel cradles for non-standard fitments?

    It’s also worth cross-referencing your track day organiser’s terms. Most reputable organisers require some proof of incident cover before you sign on. Javelin Trackdays, Bookatrack and Castle Combe Circuit all have documentation requirements, knowing what they want avoids last-minute scrambles.

    The short version: breakdown cover for track day, modified car use in the UK requires more than a standard comparison site policy. Read the small print, declare your modifications, and if your car is anything other than completely standard, look at specialist cover before you’re the person standing on a cold kerb waiting for a flatbed that isn’t coming. I’ve seen it happen. Don’t let it be you.

    Frequently Asked Questions

    Does standard AA or RAC breakdown cover work at a track day in the UK?

    No. Both the AA and RAC exclude breakdowns occurring during track days, motorsport events or on private land under their standard policies. You need a separate specialist track day recovery product to be covered in a paddock or on circuit.

    Will my breakdown cover be void if my car has modifications?

    It can be, depending on the provider. If you haven’t declared modifications that alter the vehicle’s specification or handling requirements, you may be in breach of policy terms. Declaring modifications upfront is essential; some specialist providers will cover modified vehicles explicitly where standard ones won’t.

    What specialist breakdown cover options exist for track day and modified car owners in the UK?

    Adrian Flux, Footman James and AIB Insurance all offer specialist track day and modified car breakdown products. Single-marque club memberships (BMW Car Club GB, MX-5 Owners Club) sometimes include negotiated modified vehicle cover as part of their membership packages.

    How much does specialist track day breakdown cover cost compared to standard cover?

    Expect to pay roughly £80-£150 per year for a standalone modified vehicle breakdown policy, or around £30-£60 for a per-event track day add-on through a specialist insurer. Standard policies from comparison sites run cheaper, but only cover you on public roads without modifications declared.

    Does breakdown cover work for high-mileage or older performance cars in the UK?

    Standard policies sometimes impose age limits (10-15 years) or mileage thresholds that restrict benefits like European cover or onward travel. Specialist providers generally have more flexible terms for older or high-mileage enthusiast vehicles, though premiums will reflect the additional risk.